
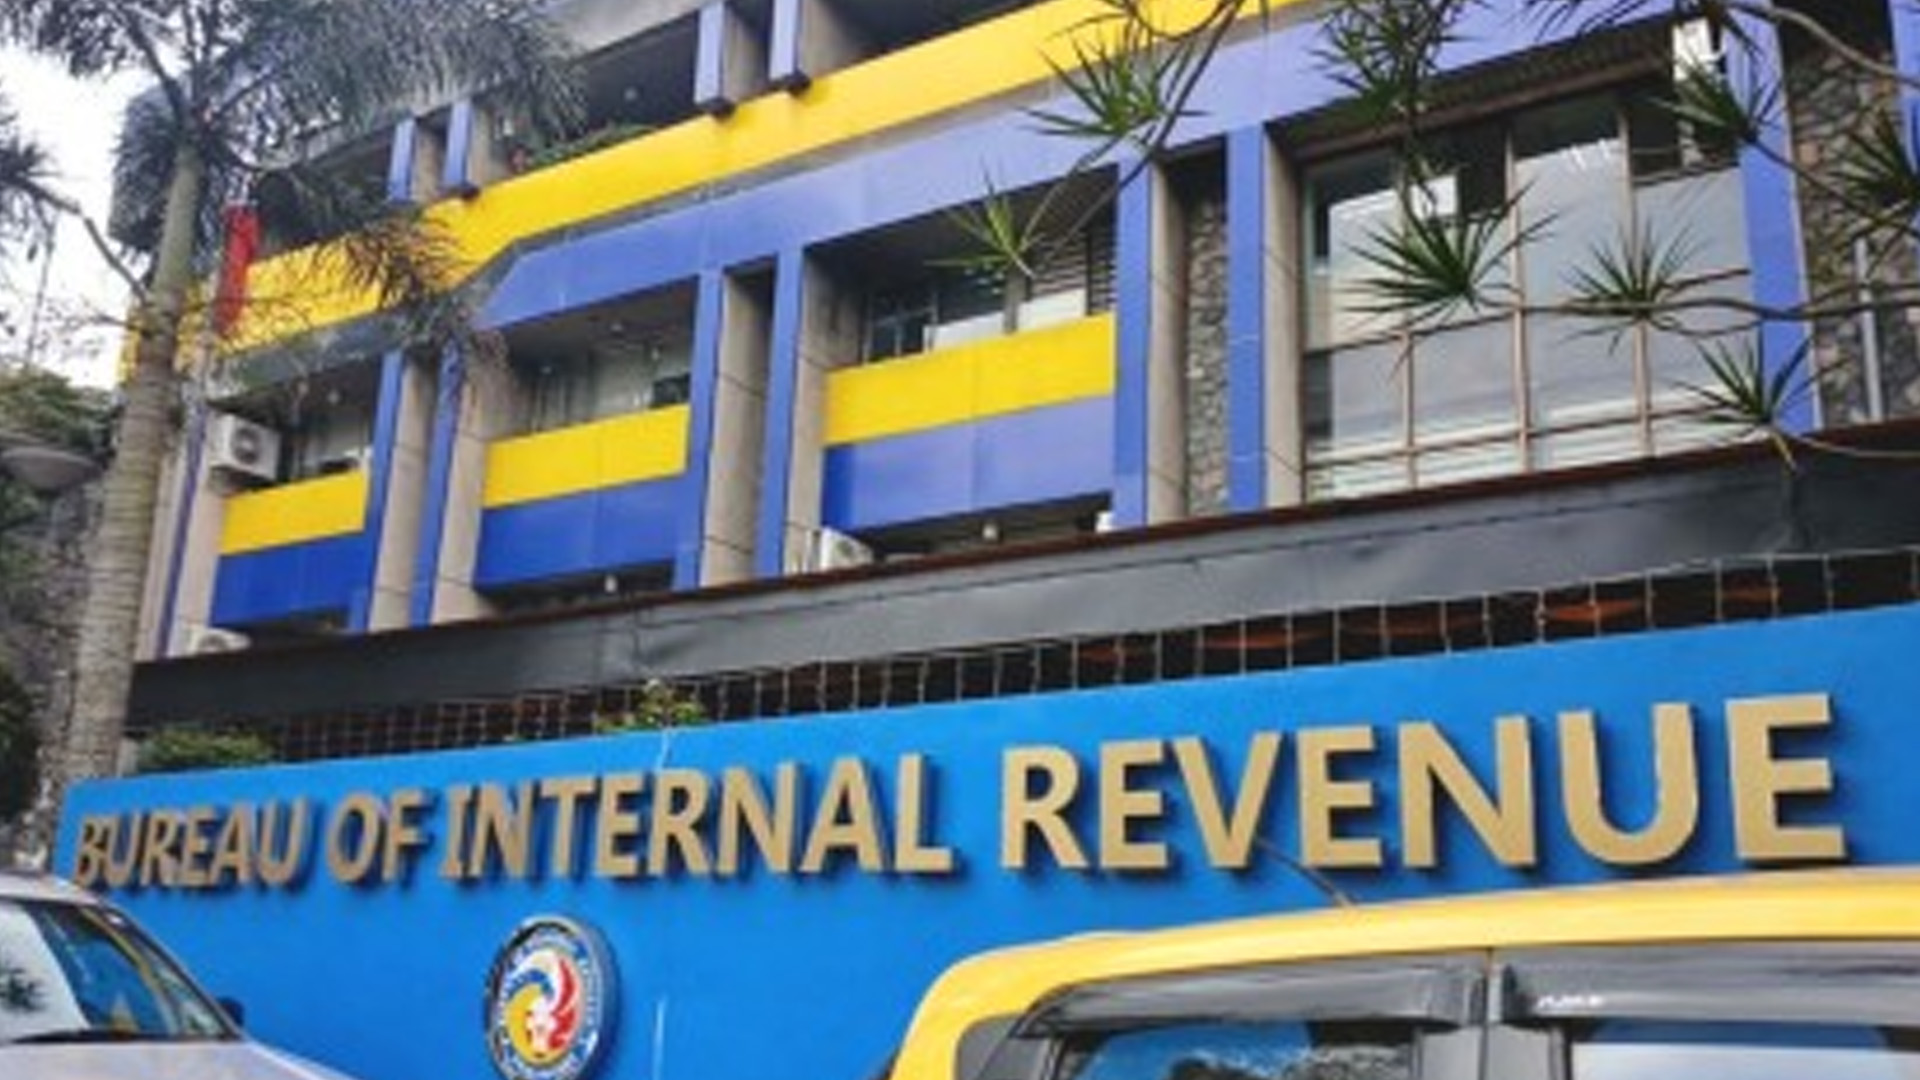

The Bureau of Internal Revenue (BIR) issued Revenue Memorandum Circular (RMC) No. 72-2026 on June 30, clarifying the tax treatment of nominee transfers of proprietary club shares that do not involve any change in beneficial ownership while removing the requirement for qualified transactions to secure a prior confirmatory ruling.
In a statement, BIR said the circular covers proprietary club shares beneficially owned by a corporation but registered in the names of corporate officers or other individuals acting only as nominees or trustees, consistent with club membership rules requiring registration in the name of a natural person.
It states that when a title to a proprietary club share is transferred from one nominee to another while beneficial ownership remains with the corporation, the transaction is not considered a sale, exchange, or donation. It is therefore not subject to capital gains tax, documentary stamp tax, or donor’s tax.
The streamlined treatment applies only if the corporation remains the beneficial owner, the nominee holds legal title under a Declaration of Trust or Trust Agreement, the proprietary club share is recorded as a corporate asset, no monetary or non-monetary consideration is given to either the outgoing or incoming nominee, and the required supporting documents are submitted.
Pending requests for confirmatory rulings involving these transactions shall no longer be acted upon.
BIR said taxpayers may instead proceed directly to the appropriate Revenue District Office to process the electronic Certificate Authorizing Registration (eCAR).
“Clearer rules lead to more efficient tax administration and greater peace of mind for taxpayers. By clarifying the proper tax treatment of these transactions and removing the need for a prior confirmatory ruling, we are reducing unnecessary administrative burden while ensuring that compliance continues to be verified through post-audit. This is another step toward making BIR processes simpler, more predictable, and easier to navigate,” BIR Commissioner Charlito Mendoza said.
“Simplifying a process does not mean relaxing compliance. We are making it easier for taxpayers to complete legitimate transactions without compromising the integrity of tax administration. The Bureau will continue to ensure compliance through documentary requirements and post-audit verification.” (PNA)