
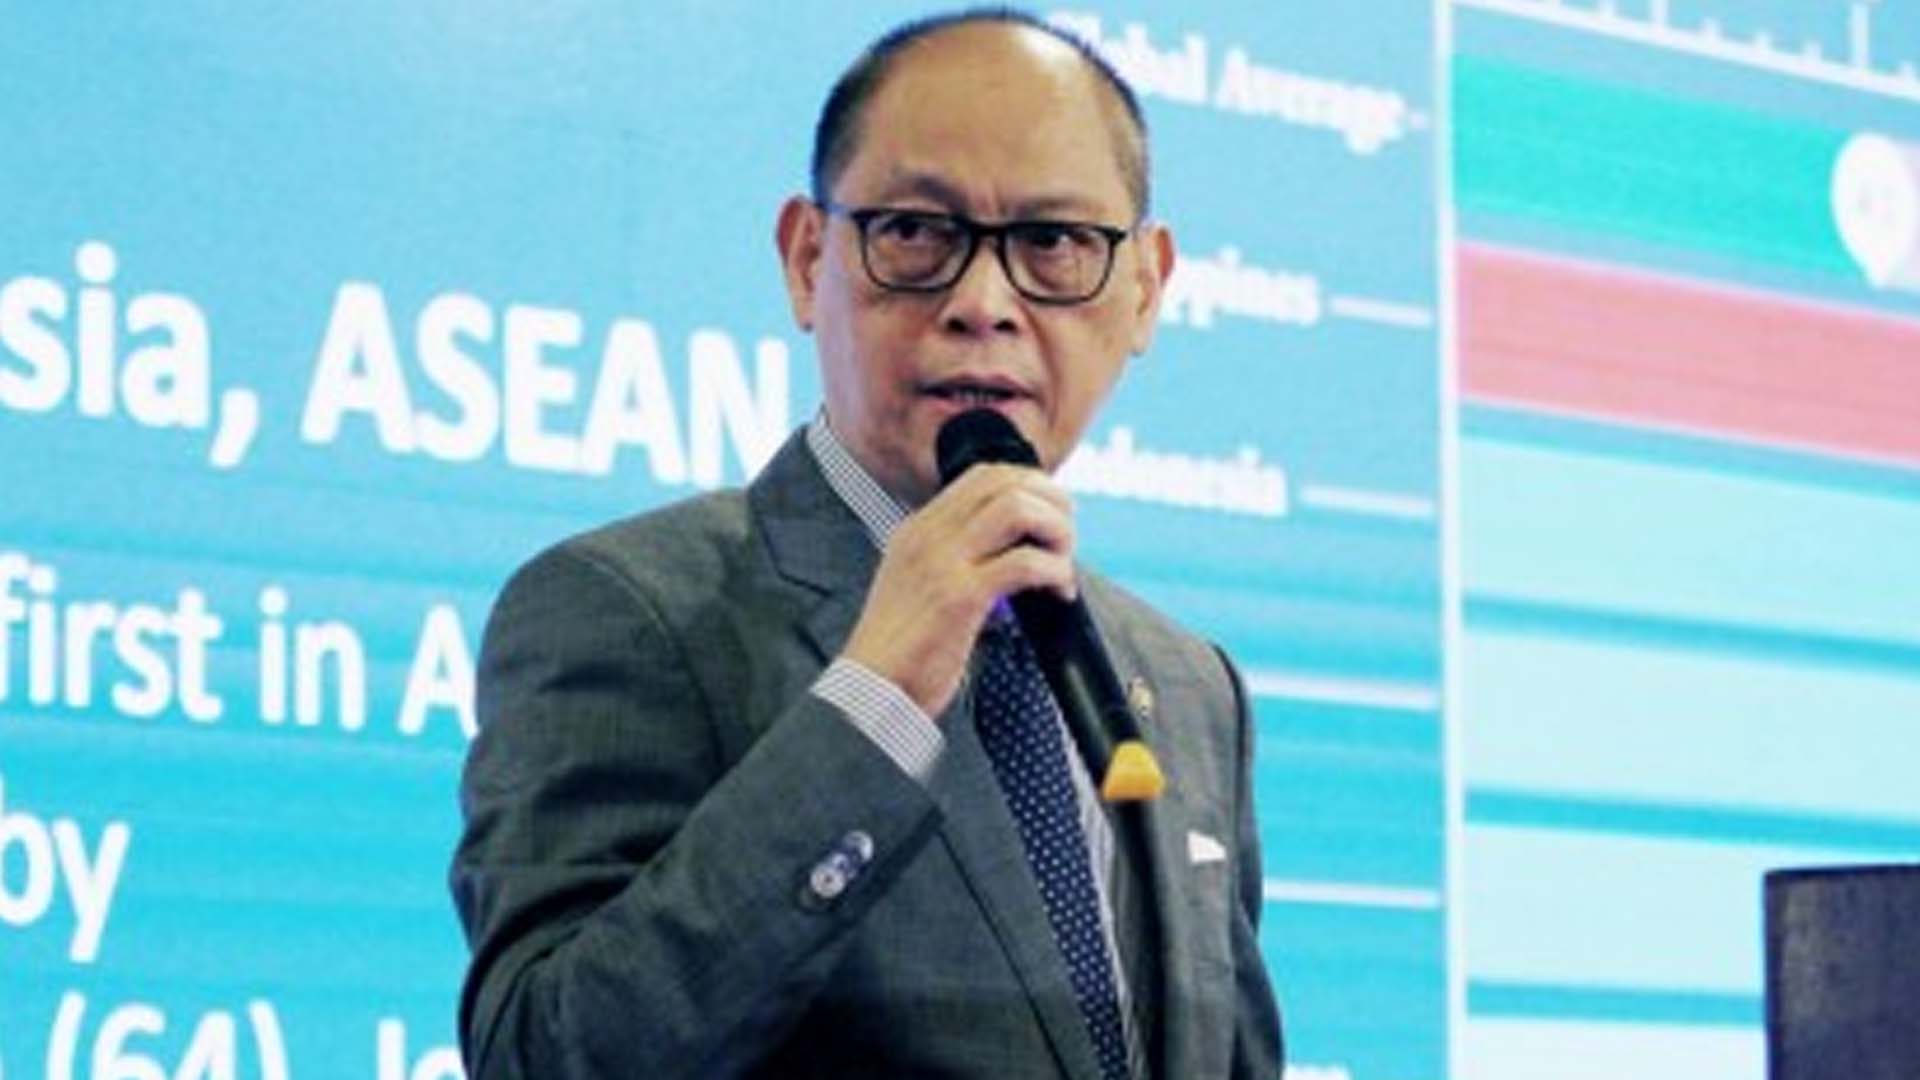

Cutting back the Bangko Sentral ng Pilipinas (BSP) key policy rates to its 2018 level will not be enough to help address the economic slowdown brought by the coronavirus disease 2019 (Covid-19) pandemic, BSP Governor Benjamin Diokno said.
“It is now clear that reverting to where we were in 2018 — policy rate at 3 percent — is no longer an appropriate policy goal. A deeper cut is warranted in response to the expected sharp economic slowdown,” he said, adding that the country “is now faced (with) a once-in-a-lifetime crisis.”
He said developments, as a result of the global pandemic, “call for bolder but appropriate moves on the part of the BSP.”
The country experienced an elevated inflation rate in 2018 due to supply-side pressures, primarily due to supply issues on rice and several food items.
That year, the rate of price increases surpassed the government’s 2 to 4 percent target band starting March when the figure hit 4.3 percent.
Inflation peaked at 6.7 percent in September and October that year.
After inflation breached the government target in the first quarter of 2018, BSP’s policy-making Monetary Board (MB) cut the central bank’s key rates by 25 basis points in May.
This was followed by another 25 basis points reduction in August, a 50 basis points reduction in September, and another 25 basis points in November.
In 2019, two more 25 basis point cuts were made, specifically in May and August.
Along with the key rate cuts are the 100 basis points cut in universal and commercial banks (U/KBs) reserve requirement ratio (RRR) in May 2018 and the total of 400 basis points reduction in banks’ RRR in 2019, with the biggest cut made for universal and commercial banks (U/KBs).
At the end of 2019, big banks’ RRR is at 14 percent while it is 14 percent for non-bank financial institutions (BSFIs) with quasi-banking functions, 4 percent for thrift banks (TBs) and 3 percent for rural banks (RBs).
These were made as inflation continue to decelerate.
In 2018, inflation averaged at 5.1 percent but it declined to 2.5 percent last year.
This year, the BSP’s key policy rates have been reduced by a total of 75 basis points, at 25 basis points last February and 50 basis points last March, as monetary officials continue to see within-target inflation rate until next year.
Last March, inflation further slowed to 2.5 percent from the previous month’s 2.6 percent, bringing the first quarter’s average to 2.7 percent. The inflation rate in March last year is higher at 3.3 percent.
Diokno said “inflation is likely to end closer to the lower bound of the 2 to 4 percent target range” this year.
Aside from the key rate cuts, BSP has reduced U/KBs’ RRR by 200 basis points last March.
This cut is half of the 400 basis points that the Monetary Board authorized Diokno to make for this year.
Diokno said, “the additional 200bps cut is forthcoming based on available data, the needs of the economy, and the utilization of the additional liquidity.” The challenge, he said, “is to cushion the impact of the economic slowdown on people, firms and the financial system.”
“The monetary authorities’ job, in coordination with fiscal authorities, is to manage a ‘soft’ landing and ensure that economic takeoff begins quickly once the pandemic fades. BSP will continue to be data-dependent keeping in mind that monetary policy works with a lag,” he added. (PNA)